©2026 Business Next Media Corp. All Rights Reserved. No.102, Guangfu S. Rd., Da'an Dist., Taipei City 106, Taiwan
AppWorks Finance & Accounting Master: How to set up a startup in Taiwan? A step-by-step guide with three common mistakes to avoid
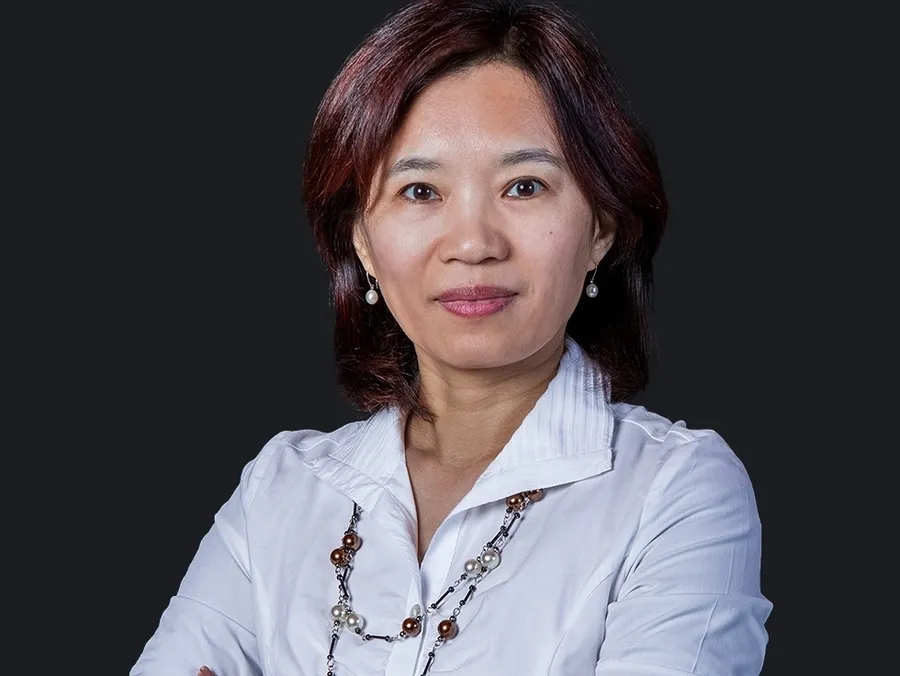
In this article, Jasmine Tsai, the Finance & Accounting Master of AppWorks, provides us with a step-by-step guide on how startups establish their companies in Taiwan and the prevalent mistakes startups have.
In 2011, Business Next launched Meet Startup as the communication platform for digital innovation and entrepreneurship. Meet Global collaborates with AppWorks, one of the largest accelerators in Taiwan with a strong founder community in Greater Southeast Asia, to publish a series of articles aiming to make the journey of starting a business in Taiwan smoother and easier.
Since 2012, AppWorks Masters Team has been helping to navigate startups through the competitive world of the business jungle, helping startups survive and stand out.
In this article, Jasmine Tsai, the Finance & Accounting Master of AppWorks, provides us with a step-by-step guide on how startups establish their companies in Taiwan and the prevalent mistakes startups have.
Advising startups with twenty years of experience at Deloitte.
Jasmine has been a senior auditing professional for nearly thirty years. She had twenty years of experience serving in the world’s leading accounting firm, Deloitte. In 2012, she met Jamie Lin, the founder of AppWorks. While Jamie shared with her the pain points startups face, Jasmine realized that her expertise can actually benefit hugely to numerous startups. Therefore, instead of continuing to serve big clients at Deloitte, Jasmine decided to step down and foster startups at AppWorks.
“While being at Deloitte, there is a very detailed breakdown of work. People have to be exceptionally good at a narrow focus. However, here at AppWorks, I have to provide advice and support extensively. The two environments are very different, and I really enjoy the vibrant, dynamic working style here,” Jasmine said.
Being the Finance & Accounting Master, Jasmine provides advice to startups on finance and accounting, and assistance on tax reporting and bookkeeping needs. With years of observation and experience, she illustrates the correct ways to establish a company and pinpoints the three most common mistakes regarding finance and accounting.
Key questions before setting up a company.
Whether to establish a company is probably the first decision entrepreneurs make when running their businesses.
“On average, it takes two months to set up a company but two years to close it. There is no turning back after opening a business, so remember to think twice, ” said Jasmine.
If startups choose to open a company without needing to do so, they waste extra time, money, and effort. On the other hand, if startups didn’t build a company when supposed to, they may not be allowed to operate certain activities, and even face legal problems.
According to Jasmine, there are three main questions to figure out when making this decision:
First, what is the main purpose of establishing a company? If startups want to conduct business activities in Taiwan, they need to complete the commerce registration, so it is recommended to build a company. Yet, if they just want to advertise products or hire a few people, a representative office would be enough.
Second, are startups aiming for government subsidies? For those yearning for getting government subsidies or joining government programs, do notice that governmental institutions prefer applicants as registered companies.
Lastly, are the rights and obligations between co-founders clearly settled? It is better to clarify the rights and obligations before a new relationship starts, which makes it easier to reach a consensus. This includes the legal business structure, the agreement of future equity transfer, and the arrangement of preemptive rights.
“Starting a business is just like getting married. You have to sign a prenup before entering a new level of relationship. It set roles, expectations, and protections for each other, ” Jasmine mentioned.
Three Steps: Decide the structure. Choose the form. Apply for registration.
Once a startup has made up its mind to set up a company, founders have to decide the legal structure of the business-- as an Unlimited Company, Limited Company, or a Company Limited by Shares. A Limited Company and an Unlimited Company are often not considered because investors hardly invest in them.
Next, choose the form of preferred business organization -- whether it is a branch office of a Foreign Company, a representative office, or a new startup. This step goes back to the previous point on the purpose of establishing a company.
Finally, comply with the registration procedures. Startup investment approvals are issued by The Investment Commission, Ministry of Economic Affairs, which usually takes around two months.
Three common mistakes startups make regarding finance and accounting
During a company’s early stage, managing the cash flow is a matter of life and death in terms of business survival. By avoiding the common financial mistakes below, startups can focus on their business development without financial stumbling blocks getting in the way.
Mistake One: Foreign founders don’t have to get paid.
For early-stage startups, it is likely that they are still struggling to make ends meet. Some founders do not want a salary because they thought this can cut down the spending on individual income tax. Nevertheless, the truth is -- in order to fulfill income requirements on their visas, they still need to receive a certain amount of salary which depends on their identity. Otherwise, the validity of the visa can be affected. Later, they may invest the money back by turning it into a loan or a share.
Mistake Two: The salary is equivalent to the hiring cost.
There is some implicit cost on hiring Taiwanese that foreign startups tend to overlook, like the cost of labor insurance and health insurance. Jasmine suggests that employers should set the budget as 150% of an employee’s salary.
As some startups may consider hiring contractors or interns, the workload and the welfare given to the worker should be balanced. For instance, asking a contractor to take responsibility as a full-time employee may lead to a labor dispute. Also, legally speaking, all interns have to be paid.
Mistake three. Audit by Reviewing Accounting Books is not suitable for startups.
At the beginning of company establishment, due to limited labor and scale, most startups choose not to hire a full-time accountant. They either entrust the tax affairs to accountancy firms or use accounting software such as Xero and QuickBooks. Either way, always remember to prepare an income statement. Only by examining the income statement can startups see revenue and loss, for both operating and non-operating activities.
When filing profit-seeking enterprise income tax, most startups entrust it to accountancy firms. Audit by Reviewing Declaration on Tax returns Expanding to the Cases Qualified is the most common method adopted. It is time-saving because startups calculate their tax by the standards directly instead of the real net profit. Nevertheless, when the net income (or loss) doesn’t meet the standard, they might in return pay more taxes.
Therefore, Jasmine suggested that Audit by Reviewing Accounting Books may be a better solution. Although it takes more time, it reflects the real situation of profits and losses.
“In the long term, developing a complete bookkeeping system is also beneficial as startups scale up, ” Jasmine noted.
©2026 Business Next Media Corp. All Rights Reserved. No.102, Guangfu S. Rd., Da'an Dist., Taipei City 106, Taiwan