©2026 Business Next Media Corp. All Rights Reserved. No.102, Guangfu S. Rd., Da'an Dist., Taipei City 106, Taiwan
Why Many AI Startups May Not Survive the Next Wave
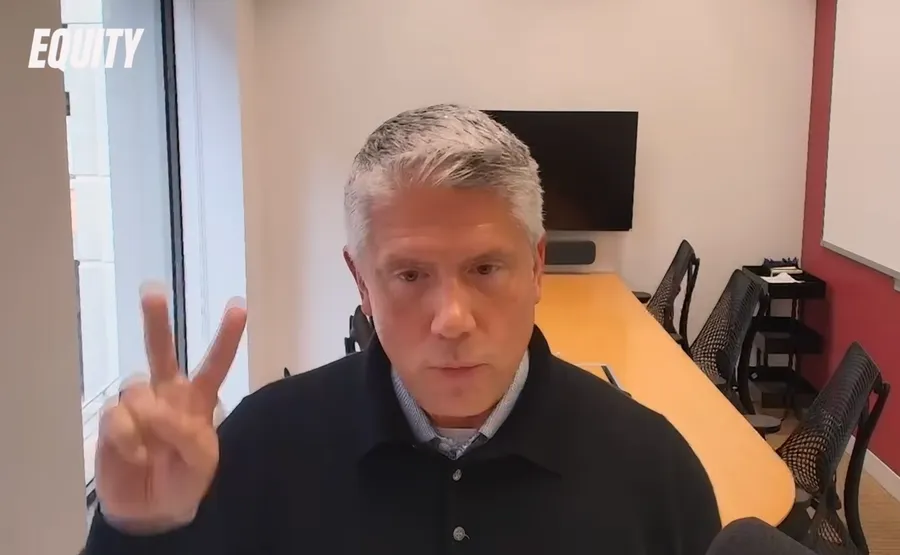
Darren Mowry, Google Vice President overseeing Google Cloud, DeepMind, and Alphabet’s startup ecosystem, has issued a stark warning: two types of once high-flying AI startup are now facing an existential moment. In his view, “LLM wrappers” and “AI aggregators” may soon struggle to survive as the AI industry matures.
The first category includes applications built on top of large language models, such as those found in the ChatGPT Store. These startups typically add a product or user experience layer to an existing model to solve a narrow problem. The second category, AI aggregators, combines multiple models into a single interface or API and routes requests between them. AI search engine Perplexity and developer platform OpenRouter are prominent examples.
Speaking on TechCrunch’s Equity podcast, Mowry said the “check engine light” is already on for many of these companies. “If you are really just relying on the backend model to do all the work, and you are essentially slapping a label on top of it, the industry does not have much patience for that anymore.” Building a business on top of Gemini or GPT-5 without meaningful differentiation creates what he described as “very thin intellectual property.” In practical terms, that means little defensible advantage.
Mowry drew on his decades of experience in cloud computing at AWS and Microsoft to explain why this moment feels familiar. In the late 2000s, a wave of startups thrived by reselling Amazon AWS infrastructure. They positioned themselves as simpler tools with integrated billing and friendlier interfaces. For a time, they generated strong margins. But once Amazon built enterprise-grade features directly into its own platform and customers became comfortable managing cloud services themselves, those middlemen quickly disappeared.
He believes the AI industry is now entering a similar phase. As Google, OpenAI, and Anthropic rapidly expand their enterprise capabilities and governance tools, the space left for startups that merely connect APIs without proprietary assets is shrinking fast.
Proprietary Data and Vertical Depth Will Decide Who Survives
If wrappers and aggregators are vulnerable, what kinds of AI startups can endure? Mowry’s answer is straightforward but demanding: build a deep moat. “You need a moat that is both deep and wide,” he said, whether through horizontal differentiation or deep specialization in a specific vertical market. Without proprietary data or meaningful domain integration, he argues, technology giants will eventually replicate the functionality at a lower cost.
He cited examples of companies that appear to be building defensible positions. Cursor, a GPT-powered coding assistant, and Harvey AI, which focuses on the legal sector, were among those he praised. These tools integrate industry-specific knowledge and workflows that general-purpose chatbots cannot easily reproduce. Their value does not come from the underlying model alone, but from how tightly the model is embedded into real professional environments.
At the same time, the competitive battlefield is moving beyond the simple chat interface. According to reporting from PYMNTS, the rise of agentic AI is reshaping how B2B product experience is defined. In the past, digital procurement often meant a marketplace-style interface that displayed products and prices. Today, agent-driven commerce is dissolving the boundaries between procurement, contracting, and settlement.
Future AI systems will not simply compare prices. They will need to interpret financing terms, credit limits, settlement speeds, and other real-time financial variables as part of automated purchasing decisions. As PYMNTS noted, if aggregation defined the first generation of B2B and workflows defined the second, payment and data structures will form the connective tissue of the third act driven by AI agents. The value layer is shifting deeper into infrastructure and financial logic.
Where Capital Is Likely to Flow Next
As the industry reshuffles, Mowry expects capital to move toward areas that create tangible value rather than surface-level functionality. He pointed to three themes that are likely to attract sustained investment.
The first is developer platforms and tools connected to what some call “vibe coding.” In 2025, tools such as Replit, Lovable, and Cursor experienced record growth. These platforms are not merely technical showcases. They cultivate developer communities and address daily workflow pain points. Their traction reflects practical utility rather than novelty.
The second theme is direct-to-consumer generative tools. By placing powerful AI capabilities directly into the hands of creators instead of limiting them to engineers, new markets can emerge. Mowry highlighted Google’s AI video generator Veo as an example. Film and television students can now transform ambitious scripts into visual content without traditional production budgets. Tools that empower creators at scale may continue to find strong demand.
The third area is cross-disciplinary deep technology, including biotechnology and climate technology. These sectors are entering a period of acceleration because AI now enables startups to analyze vast volumes of high-quality data in ways that were previously impractical. The resulting innovations are not confined to digital interfaces but extend into real-world systems with measurable impact.
Observers such as Firstpost have noted similarities between the current AI boom and previous cycles like the dot-com era or the cryptocurrency surge. Optimism may be running high once again. Yet the likely outcome is not an industry collapse, but a selective shakeout. Startups that fail to create real value or build defensible positions may disappear, while those with deep integration, proprietary data, and domain expertise stand a far better chance of enduring.
Sources: PYMNTS, Firstpost, TechCrunch, Moneycontrol, Storyboard 18
©2026 Business Next Media Corp. All Rights Reserved. No.102, Guangfu S. Rd., Da'an Dist., Taipei City 106, Taiwan